

Market Capitalization Explained: Why a $50 Stock Can Be “Bigger” Than a $500 Stock
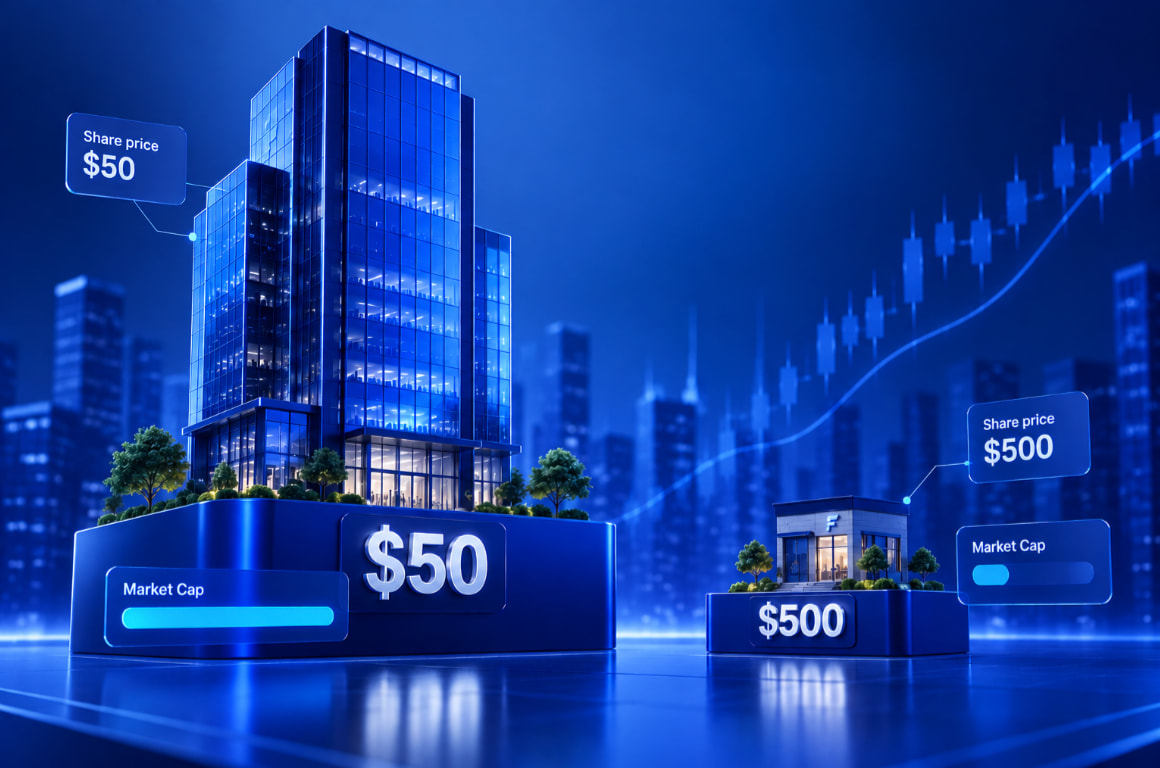
Here’s a simple investing question: Which company is more valuable - one whose shares trade at $500 or one whose shares trade at $50?
If your instinct is to choose the $500 stock, you’ve just encountered one of the most common misconceptions in investing. A stock’s price tells you surprisingly little about how large or valuable the company actually is. A $20 stock can represent a business worth hundreds of billions of dollars, while a $300 stock might belong to a much smaller company.
The metric that gives investors the bigger picture is market capitalization, usually abbreviated as market cap. Market capitalization is one of those financial concepts that looks almost too simple to deserve much attention. Yet it can tell you a great deal about the company you’re considering: its relative size, the type of risk you may be taking, how investors perceive the business, and even what role the stock could play in a diversified portfolio. At the same time, market cap has limitations. A large company isn't automatically a safe investment, and a small company isn't automatically a better growth opportunity.
What Is Market Capitalization?
Market capitalization represents the total market value of a publicly traded company’s outstanding shares. The calculation is straightforward:
Market Capitalization = Share Price × Number of Shares Outstanding
Suppose Company A has 10 million shares outstanding and each share trades at $50. Its market capitalization would be: 10 million × $50 = $500 million
Now imagine Company B trades at $200 per share but has only 1 million shares outstanding. Its market capitalization would be: 1 million × $200 = $200 million
Despite Company B having a stock price four times higher, Company A has a much larger market capitalization. That distinction is fundamental. When investors say a company is “worth $100 billion on the stock market,” they are generally referring to its market capitalization, not its share price.
Market cap also changes continuously during trading hours. If a stock rises 5% and the number of shares remains the same, its market capitalization rises by roughly 5% as well. If the stock falls, market cap falls with it. This means market capitalization isn't a fixed assessment of what a company is objectively worth. It reflects what investors are collectively willing to pay for its equity at a particular moment. And that brings us to one of the most useful lessons for beginners.
A High Share Price Doesn't Mean a Company Is Expensive
It's easy to look at two stocks and assume the one with the higher share price is somehow more valuable or more expensive. However, share price alone doesn't tell you either. Consider a simplified example:
Company B's individual shares cost more than 12 times as much. Yet Company A is worth four times more according to market capitalization. Why?
Because ownership of a company is divided into shares, and different companies have dramatically different numbers of shares outstanding.
Think of a tasty pizza. One pizza might be divided into eight slices and another into 16. The size of one slice doesn't tell you which pizza is bigger, you need to know how many slices exist and how large the whole pizza is.
Shares work in a similar way. This is also why stock splits can dramatically change a company's share price without changing its market capitalization at the moment of the split. If a company conducts a 2-for-1 stock split, investors receive twice as many shares, while the price of each share is approximately halved. The pieces become smaller, but the underlying pie hasn't suddenly changed in size.
For investors, this leads to an important rule: Never judge whether a stock is “cheap” or “expensive” based on its share price alone. A $10 stock isn't necessarily cheap, and a $500 stock isn't necessarily expensive. Valuation requires a much deeper look at the business.
Large-Cap, Mid-Cap, and Small-Cap Stocks: Why Size Matters
Market capitalization becomes especially useful when comparing companies and understanding their general risk profiles. Stocks are commonly grouped into categories such as large-cap, mid-cap, and small-cap. You may also encounter mega-cap and micro-cap stocks.
There is no single universal cutoff used by every index provider or financial institution, so the ranges should be treated as broad classifications rather than strict rules. A common framework looks roughly like this:
So why should an investor care? Because company size often influences how a stock behaves.
Large-Cap Stocks: Scale and Stability
Large-cap companies tend to be established businesses with significant revenue, recognizable brands, and mature operations. Think of companies such as Apple, Microsoft, or Coca-Cola.
Their size can provide certain advantages. They may have diversified revenue streams, easier access to financing, established customer bases, and greater resources for surviving difficult economic periods. That doesn't make their stocks risk-free.
Large companies can still lose market share, make poor strategic decisions, become overvalued, or experience substantial stock-price declines. However, compared with very small businesses, large-cap companies are generally more established. There is also a trade-off. A company already worth hundreds of billions or even trillions of dollars may need to generate enormous amounts of additional business to double in size.
Small-Cap Stocks: More Room to Grow, More Room to Go Wrong
Small-cap companies sit at the other end of the spectrum. These businesses are often at earlier stages of development and may operate in niche or emerging markets. That can create exciting opportunities. A $1 billion company only needs to add $1 billion in market value to double. A $1 trillion company needs another $1 trillion.
Of course, investing isn't nearly that simple. Smaller businesses may have weaker balance sheets, fewer customers, less predictable earnings, lower trading liquidity, and greater sensitivity to economic downturns. Their share prices can also be much more volatile. That creates the fundamental small-cap trade-off: greater potential growth often comes with greater uncertainty.
Mid-Cap Stocks: Somewhere in Between
Mid-cap companies are sometimes overlooked because they don't have the familiarity of large-cap names or the “next big thing” appeal associated with smaller companies. However, they can occupy an interesting middle ground.
Many have already demonstrated that their business models work but still have meaningful opportunities to expand. For investors, this can potentially offer a combination of established operations and future growth, although, as always, individual company fundamentals matter far more than the category itself.
Why Market Cap Matters When Building a Portfolio
Market capitalization becomes particularly useful when you stop analyzing individual stocks and start thinking about your portfolio as a whole. Imagine an investor owns ten companies. At first glance, that sounds diversified; however, suppose nine of those companies are small, speculative technology businesses. The investor owns ten stocks, but the portfolio may still be heavily exposed to the same type of risk.
Market-cap diversification can help investors understand this problem. A portfolio might combine larger established businesses with mid-sized companies and selected smaller businesses. Each group can behave differently depending on economic conditions, interest rates, investor sentiment, and market cycles.
This doesn't mean every portfolio needs an equal allocation to every market-cap category. The appropriate mix depends on factors including your time horizon, financial goals, tolerance for volatility, and overall strategy. Market capitalization can also help investors understand the indexes they own.
Many major stock indexes are market-cap weighted. This means larger companies receive a greater weighting in the index than smaller ones. As a result, owning an index fund doesn't necessarily mean your money is distributed equally across every company in that index. A handful of extremely large businesses can have a meaningful influence on overall index performance. That's a detail worth understanding, especially when a small group of mega-cap stocks is responsible for a significant portion of a market's gains or losses.
What Market Capitalization Doesn't Tell You
Market cap is useful, but this is where investors need to be careful. Market capitalization tells you how the market values a company's equity. It doesn't tell you whether that valuation makes sense. A $100 billion company isn't necessarily financially stronger than a $50 billion company. And a $1 billion company isn't necessarily undervalued simply because it's small.
Market cap alone doesn't tell you about:
revenue
profitability
debt
cash flow
competitive advantages
future growth
management quality
valuation relative to earnings
Consider two companies that both have a $20 billion market cap. Company A might generate $10 billion in annual revenue and substantial free cash flow. Company B might generate $1 billion in revenue while operating at a loss. Their market capitalizations are identical, but the investment cases could hardly be more different. This is why market cap should be viewed as one piece of the puzzle, not as a final investment signal.
There's another important distinction: market capitalization is not the same as enterprise value. Market cap looks primarily at the value of a company's equity. Enterprise value takes a broader approach by also considering factors such as debt and cash.
This can matter significantly when comparing businesses with very different capital structures. Two companies could have similar market caps while one carries billions of dollars more debt than the other. Looking only at market capitalization would miss that difference.
How Investors Can Use Market Cap in Practice
So, if market cap can't tell you whether a stock is a good investment, what is it actually useful for? Think of it as a starting point for understanding the type of company you're analyzing. Before buying a stock, market capitalization can help put expectations into perspective.
If you're looking at a $500 million company, ask yourself whether you're prepared for the volatility and business risks that can accompany smaller companies. If you're evaluating a $2 trillion business, consider how much future growth may already be reflected in its enormous valuation. You can then combine market cap with other metrics.
For example, an investor analyzing a company might look at:
Market cap + revenue to understand how highly the market values its sales.
Market cap + earnings to evaluate its valuation relative to profitability.
Market cap + free cash flow to assess how much cash the business generates relative to its equity value.
Market cap + debt to understand whether the company's apparent size hides a highly leveraged balance sheet.
This is where market capitalization becomes genuinely useful. Not as an answer, but as context. It helps investors ask better questions. And better questions are usually much more valuable than simply looking for one perfect financial metric.
Conclusion
Market capitalization is one of the simplest concepts in investing, but understanding it correctly can immediately improve the way you look at stocks. It teaches you that share price and company size are not the same thing. It helps distinguish between small emerging businesses and established global corporations. And it provides useful context for understanding portfolio diversification, index construction, risk, and valuation. Perhaps most importantly, market cap reminds us that numbers need context.
A company worth $500 billion isn't automatically a better investment than one worth $5 billion. A small-cap stock isn't automatically a hidden opportunity. And a low-priced share isn't automatically cheap. The real question is always what you're receiving in exchange for the price you're paying. That's why market capitalization works best as the beginning of your research rather than the end of it.
Use it to understand the size of the business. Then look deeper at earnings, revenue, cash flow, debt, competitive position, valuation, and long-term potential. Because knowing how big a company is can tell you a lot. Understanding why the market believes it should be worth that much is where investing becomes truly interesting.